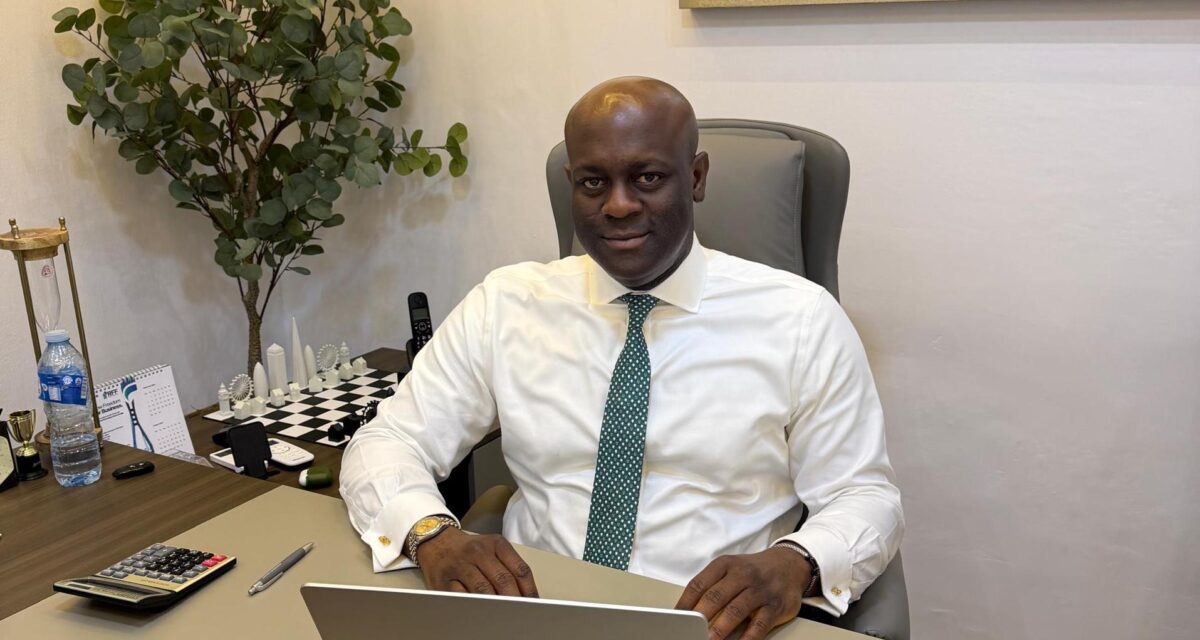

Wole Shenbanjo, is an entrepreneur and monetary providers government and the Group CEO of Shenbee Investments. He has pursuits spanning monetary providers, funding markets and journey administration, and is the founding father of Saturn Credit Limited, a monetary providers firm targeted on offering credit score options to people and companies. In this interview with Chinedu Eze, he discusses the evolving credit score panorama in Nigeria, the challenges going through companies and debtors, and his imaginative and prescient for constructing Saturn Credit
How would you describe the present state of entry to credit score in Nigeria, notably for people and SMEs, and what are the largest boundaries stopping extra Nigerians from accessing formal financing?
I believe entry to credit score in Nigeria stays a big problem, notably for people and small and medium-sized companies.
There is credit score out there out there, however the query is whether or not the proper financing is reaching the proper folks on the proper time and on phrases that make sense.
For many people and SMEs, the boundaries embrace documentation necessities, the time it takes to course of purposes, the price of borrowing and, in some instances, the problem of demonstrating creditworthiness inside conventional lending buildings.
For SMEs specifically, there could be a important hole between the chance they’ve and the capital out there to execute it.
A enterprise might have a real contract or a viable alternative however nonetheless wrestle to entry the working capital required to ship.
I believe the chance for the business is to make credit score extra accessible with out changing into much less disciplined about threat.
The reply isn’t merely to lend extra money. It’s to make higher credit score out there to extra folks.
How have inflation, rates of interest, exchange-rate pressures and the broader financial setting modified the best way Nigerian companies and people method borrowing and financing?
The present setting has made each companies and people rather more aware of how they use capital.
When the price of doing enterprise rises, each naira has to work more durable. Businesses are subsequently trying rather more rigorously at money circulate, working capital and the price of financing.
For people, affordability and compensation capability have additionally grow to be rather more necessary concerns.
I believe the present setting has strengthened an necessary precept: borrowing has to make financial sense.
Credit ought to ideally assist a person or enterprise obtain one thing productive — whether or not that’s managing a cash-flow requirement, buying an asset or benefiting from a real enterprise alternative.
It additionally means lenders have to be extra disciplined. You can not take a look at lending merely from the attitude of how a lot you’ll be able to disburse. You have to contemplate the shopper’s capacity to repay and the underlying economics of the transaction.
The present setting has made that self-discipline much more necessary.
Why does entry to reasonably priced and accountable credit score stay vital to the survival and development of Nigerian SMEs, and what are the implications when viable companies can not get hold of financing?
SMEs are a vital a part of the Nigerian financial system, and entry to capital can decide whether or not a enterprise is ready to make the most of a possibility or not.
Imagine an organization that has secured an order however wants working capital to fulfil it. The enterprise could also be basically sound, however with out entry to financing, that chance might disappear.
The similar applies to buying gear, increasing capability or managing non permanent cash-flow pressures.
The penalties transcend the person enterprise. When viable companies can not entry capital, they might not be ready to develop, make use of extra folks or take part absolutely in financial exercise. But I might stress the phrase accountable.
We shouldn’t create a tradition the place the reply to each monetary problem is solely to borrow.
The goal ought to be to create a credit score system the place viable people and companies can entry acceptable financing, whereas lenders keep the self-discipline to be certain that the financing is sustainable.
What wants to change inside Nigeria’s lending business to make the credit score course of extra accessible, clear and customer-friendly whereas nonetheless defending lenders in opposition to extreme threat?
I believe we want to enhance your entire buyer journey.
Customers ought to have the opportunity to perceive what they’re making use of for, what data is required, how selections are made and what their obligations shall be. At the identical time, lenders want to strengthen the best way they assess threat.
These two issues don’t have to battle.
Technology and higher knowledge might help lenders make sooner and doubtlessly better-informed selections, whereas sturdy underwriting and portfolio monitoring defend the establishment.
I additionally assume the business wants to grow to be extra customer-centric.
When any person approaches a monetary establishment for credit score, there’s normally an actual cause behind that request. Understanding that want is necessary.
For me, the best lending establishment is one that’s accessible sufficient for patrons to have interaction with, clear sufficient for them to belief, and disciplined sufficient to defend the integrity of its stability sheet.
Technology, different knowledge and digital monetary providers are reshaping lending globally. How can Nigerian lenders use these instruments to enhance credit score evaluation and broaden entry with out compromising accountable lending and client safety?
Technology can considerably enhance the best way we ship monetary providers.
It could make purposes sooner, scale back pointless paperwork, enhance knowledge assortment and assist establishments make extra knowledgeable selections.
Data is especially necessary as a result of conventional measures of creditworthiness don’t at all times inform the total story about a person or enterprise.
However, expertise ought to be seen as an enabler, not an alternative to judgement.
We nonetheless want sturdy credit score insurance policies, acceptable threat controls and a correct understanding of the shopper.
And there has to be transparency round how buyer data is used.
The purpose ought to be to use expertise to enhance entry and decision-making, not to take away accountability from the lender.
I believe the establishments that get that stability proper shall be in a powerful place because the Nigerian monetary providers business evolves.
You not too long ago launched Saturn Credit. What particular hole in Nigeria’s lending market did you establish, and the way is Saturn’s method designed to handle a few of the challenges debtors presently face?
The considering behind Saturn got here from seeing a reasonably easy downside: there are numerous people and companies with reliable financing wants, however accessing acceptable credit score isn’t at all times as simple appropriately.
I’ve been an entrepreneur for quite a few years, and thru constructing companies similar to Shenbee Travels, I’ve seen first-hand how necessary entry to capital and efficient cash-flow administration will be to a rising enterprise.
When you’re operating a enterprise, alternatives don’t at all times arrive when your money circulate is at its strongest. Sometimes a enterprise doesn’t want an enormous sum of money. It might merely want the proper financing on the proper time to execute a possibility or handle a brief cash-flow requirement.
That expertise, along with my publicity to monetary markets, made the credit score house notably attention-grabbing to me.
So, with Saturn, we’re taking a look at how we are able to make the financing expertise extra accessible, responsive and easy, whereas nonetheless being very disciplined about credit score threat.
We don’t need to construct a enterprise round merely pushing cash out.
We need to construct a enterprise round understanding the shopper, understanding the danger and offering acceptable financing.
That’s the muse we’re making an attempt to set up.
Given the dangers related to lending in as we speak’s financial setting, how does Saturn Credit stability increasing entry to finance with accountable lending, efficient threat administration and the flexibility of consumers to repay?
For me, this is likely one of the most necessary questions on constructing Saturn.
Growth is necessary, however high quality development is extra necessary than development for its personal sake.
Having constructed and operated companies myself, I perceive that development and money circulate don’t at all times transfer on the similar tempo. That expertise informs how I take into consideration credit score.
We have to perceive who we’re lending to, why they want the financing and whether or not there’s a affordable foundation for compensation.
That means having the proper folks, processes, credit score evaluation and monitoring programs in place.
We even have to recognise that lending is inherently a threat enterprise. What issues is having the self-discipline and programs to handle that threat correctly.
Our ambition is subsequently not to construct the biggest mortgage e-book as rapidly as potential.
It is to construct a wholesome, sustainable credit score enterprise.
If we are able to broaden entry to financing whereas sustaining good credit score high quality and treating clients pretty, then I imagine we’re constructing one thing that may final.
Looking forward, what position do you imagine indigenous Nigerian monetary establishments can play in deepening entry to credit score, and what would you want Saturn Credit to contribute to Nigeria’s monetary ecosystem over the following 5 to 10 years?
I believe indigenous monetary establishments have a vital position to play as a result of we perceive the market that we function in.
My personal entrepreneurial journey has taken me throughout completely different sectors. Through Shenbee, we’ve constructed companies in areas together with journey administration and monetary providers, and that have has strengthened my perception that Nigerian companies want establishments that perceive the realities of working on this market.
Nigeria has a really entrepreneurial inhabitants, however the monetary wants of Nigerians should not at all times equivalent to these of different markets.
There is a chance for native establishments to develop monetary options which are related to our realities, whereas sustaining sturdy requirements of governance, threat administration and buyer safety.
For Saturn, we’re beginning with credit score, however the long-term ambition is greater than merely being a lender.
Over the following 5 to ten years, I’d like Saturn to develop right into a revered Nigerian monetary establishment with a powerful status for accountable financing and wonderful buyer expertise. We need to construct progressively and earn the proper to broaden. Ultimately, I would really like folks to take a look at Saturn and say: “This is an institution that understands its customers, manages its risks properly and can be trusted with their financial needs.” That’s the sort of establishment I’m serious about constructing.