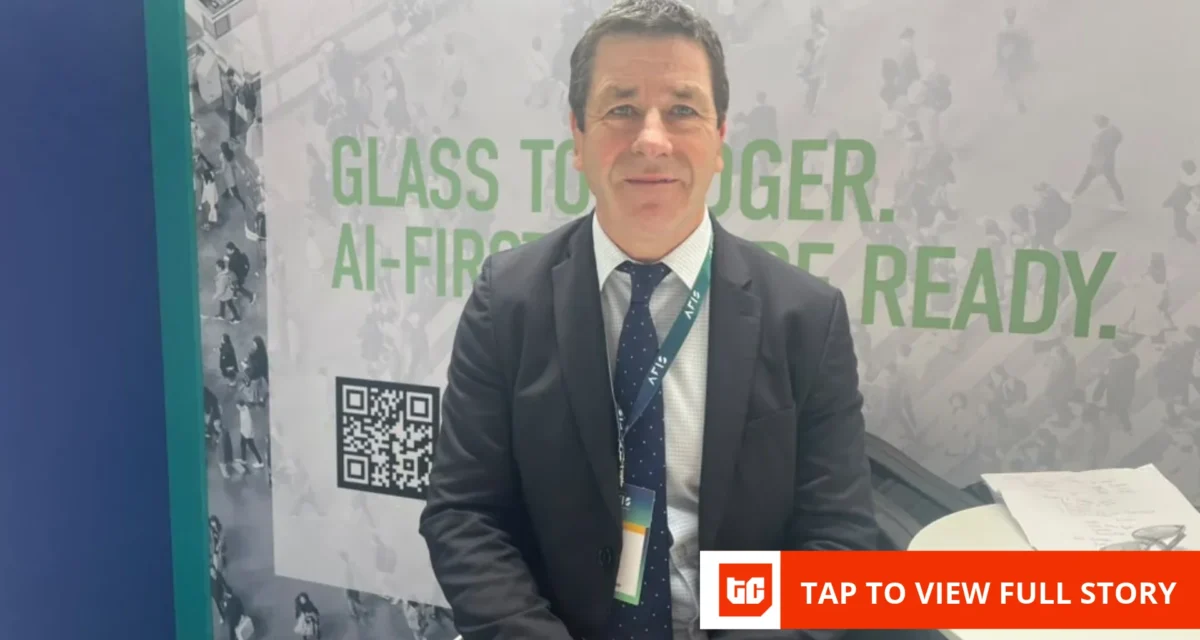

Speaking on the sidelines of the African Financial Industry Summit 2026 in Luanda, Fintan Byrne, chief government officer of digital banking platform CR2 (now a part of Morocco’s HPS Group), argues that African banks are eroding market share, that shopper expectations are shifting towards immediate, cross-border companies, and that front-end technique is proving dangerously insufficient to find out the subsequent decade of continental finance. GODFREY GEORGE stories.
For the previous decade, industrial banks throughout Africa have handled the launch of a smartphone software because the definitive proof of digital transformation. Yet, as agile fintechs erode market share and shopper expectations shift towards immediate, cross-border companies, that front-end technique is proving dangerously insufficient.
Inside the assembly rooms of the Africa Financial Industry Summit (AFIS) in Luanda, business veterans are delivering a blunter evaluation: rolling out standalone digital functions with out overhauling underlying infrastructure is merely papering over legacy cracks.
“Simply launching a mobile application does not solve any problems on its own,” says Fintan Byrne, chief government officer of CR2. “Innovation for the sake of innovation, or simply introducing another application, does not necessarily deliver value. It requires a comprehensive programme built around the question of what value we are trying to create, what problem we are trying to solve, and what friction we are trying to reduce.”
Byrne, an Irish banking software program government with practically three a long time of expertise throughout the worldwide funds panorama—from retail banking and service provider buying to senior roles at card schemes like Mastercard—now leads CR2 beneath the umbrella of Morocco-headquartered multinational HPS Group.
Between CR2 and HPS, the mixed enterprise brings collectively six a long time of funds engineering and serves practically 60 industrial lenders globally.
In Africa, that footprint contains tier-one establishments comparable to Absa, Standard Chartered Bank, Standard Bank, and Access Bank, in addition to 5 industrial lenders in Egypt, together with Commercial International Bank (CIB), and several other establishments throughout East Africa and Ethiopia.
For Byrne, the dilemma dealing with African banking chiefs is twofold: legacy lenders must defend their conventional department and ATM distribution footprints whereas concurrently investing in complicated digital capabilities to fend off each home banking rivals and digital-first fintech insurgents.
The friction check and the platform lure
To separate real transformation from digital self-importance tasks, Byrne topics each technological deployment to what he calls the “friction test.”
“I always ask my team and the CEOs I engage with to consider what I call the friction test,” Byrne explains.
“Will the solution make something cheaper? Will it save someone money? Will it be easier to use? Will it save time? We need to go through these questions to understand whether the investment we are making will deliver significant benefits.”
The structural mistake many African lenders make, in keeping with Byrne, is buying remoted, point-to-point software program options for particular person banking capabilities.
One vendor is employed for buyer onboarding, one other for mortgage origination, a 3rd for cell interfaces, and a fourth for company banking. The result’s an costly, fragmented IT property that slows down innovation and frustrates prospects.
CR2’s counter-strategy focuses on platformisation: deploying a unified underlying structure during which capabilities may be incrementally switched on, with out embarking on protracted core-banking overhauls.
“One of the challenges facing banks is that they invest in multiple individual solutions without necessarily connecting them effectively,” Byrne says.
“We encourage banks to invest in a platform and then unlock the capabilities they need from that platform. If a bank wants to develop a specific customer journey for onboarding or loan origination, it should be able to unlock that capability through the platform without having to invest in an entirely new platform or undertake another integration.”
Where banks have executed this shift, the balance-sheet affect has been tangible. In North Africa, Byrne factors to Egypt’s CIB, which utilised channel segmentation to route routine transactions away from costly department networks to self-service digital and assisted channels, thereby lowering its operational cost-to-income ratio and accelerating buyer acquisition.
AI within the construct and run phases
While enterprise software program kinds the spine of digital banking, the dialog at AFIS 2026 has been dominated by synthetic intelligence. Yet, in markets the place roughly 85% of financial exercise happens within the casual economic system, the sensible software of frontier know-how is commonly met with scepticism.
When requested how an AI-first banking posture advantages an off-the-cuff market lady promoting fish in Luanda or Lagos, Byrne splits the know-how’s lifecycle into two distinct dimensions: the “build phase” and the “run phase”.
In the construct section, banks must engineer their technical structure to be machine-readable from day one, utilizing fashionable software programming interfaces (APIs) and knowledge pipelines that accommodate rising paradigms comparable to agentic commerce—during which autonomous software program brokers make buying and monetary selections on behalf of customers.
The run section, nonetheless, is the place rapid industrial worth is unlocked, significantly in credit score underwriting and fraud prevention.
“How can AI make businesses more efficient in their day-to-day operations?” Byrne asks. “Credit scoring and behavioural scoring are critical areas. You mention the market woman selling fish: how can we better understand her business cash flow and operations? Perhaps we can use that information to provide her with instant credit to support her enterprise. We could also understand the seasonal nature of her trade and take that into account when assessing her financial needs.”
By substituting classical, immovable collateral—comparable to actual property titles—with transaction analytics and cash-flow knowledge captured via cell wallets and company banking networks, lenders can lastly underwrite the continent’s huge unbanked and underbanked service provider base.
Crucially, Byrne argues that this identical intelligence must be turned outward to defend establishments towards escalating monetary crime. Rather than merely flagging suspicious transactions autopsy, machine studying fashions are being deployed on the infrastructure degree to determine behavioural anomalies and predict fraudulent transactions earlier than settlement happens.
Stablecoins, CBDCs, and orchestration
Beyond credit score and fraud, African banking establishments are navigating an evolving financial panorama marked by central financial institution digital currencies (CBDCs), stablecoins, and tokenised property.
Rather than viewing digital currencies as an instantaneous existential menace to industrial banking, Byrne argues that lenders must deal with them as each shops of worth and fee mechanisms. More importantly, establishments mustn’t assume that the rise of digital cash requires tearing down legacy rails.
To clarify the coexistence of latest and previous fee rails, Byrne makes use of an automotive parallel.
“When electric cars were introduced, we did not build entirely new roads for them,” Byrne observes. “We continued using the existing roads. However, we needed additional infrastructure, such as charging stations. The same principle applies to digital money. We can leverage existing payment infrastructure, but additional capabilities and investments will be necessary.”
This actuality elevates the strategic significance of fee orchestration—the technical plumbing that enables disparate fee rails, card schemes, cell cash wallets, and digital tokens to interoperate easily.
As stablecoins achieve traction for cross-border commerce settlements in currency-starved markets, industrial banks will want strong orchestration platforms to handle on-ramps and off-ramps, guaranteeing that prospects can convert fluidly between sovereign fiat, digital currencies, and financial institution deposits inside a single safe surroundings.
Trust and safety
Throughout the discussions in Luanda, the undercurrent of each technological transition—whether or not AI, agentic buying, or stablecoin rails—stays institutional safety.
Without regulatory certainty and ironclad cybersecurity, Byrne cautions that digital initiatives threat catastrophic reputational failure, noting that banking operates beneath essentially totally different social and regulatory contracts than speculative tech sectors.
“The entire business of banking is built on trust,” Byrne notes. “Therefore, any new evolution or innovation must be introduced with that consideration in mind. Security may not be the most exciting subject, but it is fundamental. Trust is very difficult to build but incredibly easy to lose.”
Pointing to high-profile controversies and enforcement actions which have rocked the broader crypto and change sector lately, Byrne stresses that conventional banking can not afford the lax compliance postures usually related to decentralised finance. If a regulated industrial financial institution had been to lose billions of {dollars} in buyer deposits, the systemic contagion and institutional fallout can be existential.
The street forward
Looking in direction of the subsequent 5 years, Byrne envisions a structural consolidation in how African banks have interaction with know-how suppliers.
The period of bespoke, disconnected software program experimentation is winding down, giving method to enterprise partnerships targeted on scalability, platform resilience, and hyper-personalisation.
As digital adoption matures, the aggressive battlefield for African lenders will centre on treating prospects not as broad demographic classes, however as distinct micro-segments.
“We are moving towards what we traditionally describe as a segment of one,” Byrne says. “If a bank has a high-net-worth customer, how does it ensure that the customer receives the right service, experience, and capabilities for their particular needs? The same applies to mass-affluent customers, the mass market, students, and people who are just beginning their financial journeys.”
For Byrne, the message to African banking management gathered in Luanda is unmistakable: the establishments that survive the subsequent decade of disruption is not going to be those who launch the sleekest standalone cell functions, however those who put money into the unglamorous, heavy-duty platform plumbing required to orchestrate funds, automate intelligence, and safeguard institutional belief.