
Walk down any busy Nigerian avenue, and you’re strolling by means of an financial system. Someone is welding a gate. Someone is sitting behind a POS machine below an umbrella. Someone is working a kitchen out of a entrance room and feeding half the road by lunchtime.
The nation’s popularity for enterprise is not flattery we pay ourselves. Nigeria has roughly forty million businesses. Only India and Indonesia are reckoned to have extra. Whatever else has gone incorrect right here, Nigerians haven’t stopped beginning issues.
But type these businesses by measurement, utilizing the courses the nationwide survey itself makes use of, and the image turns unusual. Of the 39.7 million enterprises within the final depend, 33 million are nano businesses, that means one or two folks. Another 5.9 million are micro, with three to 9.
That leaves 617,248 small corporations. And 53,199 medium sized ones, the kind with a actual payroll and a steadiness sheet a financial institution may learn.
That is one enterprise in each 745. Nigeria is a nation crowded with businesses and almost empty of firms.
The distinction is not a matter of phrases. A enterprise is one individual’s residing. An organization is a factor that outlasts the week: it carries workers, buys machines, indicators contracts it may be sued over, and retains books that somebody exterior the household can verify. Almost the whole lot a trillion greenback financial system is fabricated from comes from the second variety.
The check is what a agency can do, not what it is referred to as. A enterprise will be completely effectively integrated and nonetheless be one individual’s residing, and a nice many Nigerian firms are precisely that.
You can see what the scarcity prices us in a single comparability. Nigeria’s micro, small and medium corporations present about 88% of all employment and a little below half of nationwide output. They account for roughly 6% of what the nation sells overseas. So they carry almost 9 jobs in each ten, and virtually none of what Nigeria sells to the world.
Medium-sized corporations are the place an financial system learns to do issues correctly. They are giant sufficient to purchase a machine and maintain it busy, to make use of somebody whose solely job is high quality, to fulfill a overseas purchaser’s commonplace after which fill the repeat order that follows. A person promoting from a tray can’t do any of that, nevertheless laborious he works. There is no association of forty million trays that provides as much as an trade.
That is a declare about functionality and never about advantage. Size doesn’t make a agency good. It makes sure varieties of fine doable.
The typical rationalization for all this is cash, and it is a good rationalization so far as it goes. I’ve written right here about a monetary system that finds it simpler to lend to the federal government than to a producer. The latest World Bank survey of Nigerian corporations bears it out: 28% of small corporations say getting finance is the one largest impediment they face. That survey covers formal corporations of 5 workers or extra, so the corporations from right here on are the bigger, countable type.
But comply with that quantity up the dimensions ladder and it comes aside in your palms. Finance is the most important impediment for 28% of small corporations, 16% of medium ones, and 1.7% of enormous ones.
Both issues are true without delay. The nice mass of small and casual businesses is starved of credit score. The few corporations that attain measurement have largely solved it.
So credit score explains why a Nigerian enterprise struggles. It doesn’t clarify why so few of them ever cross over.
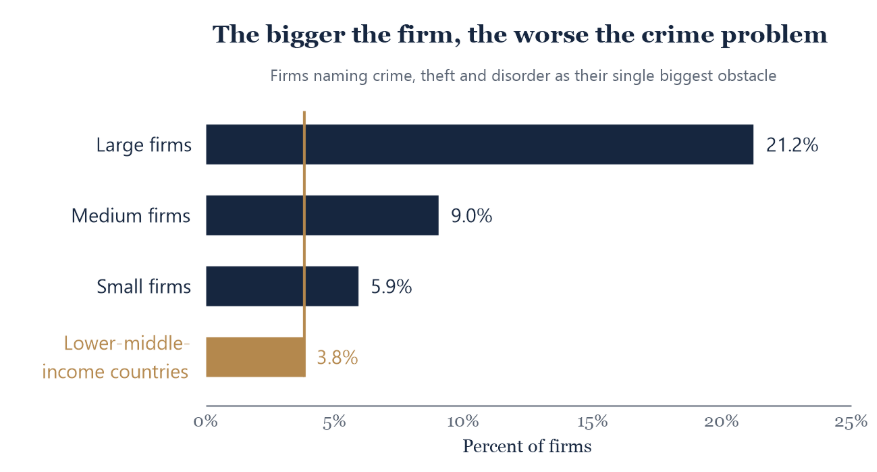
Something else is ready on the opposite aspect. Ask Nigerian corporations to call their single biggest impediment and crime is chosen by 6% of small corporations, 9% of medium corporations, and 21% of enormous ones. Corruption climbs the identical staircase, from 6% to fifteen%.
Growth doesn’t elevate the burden. It modifications which burden you carry.
That query has a lure in it. It asks corporations to rank their troubles, to not measure them. When finance stops being a giant agency’s worst drawback, one thing else takes the title.
So look as an alternative at what corporations spend. Spending is a measurement, not an opinion. The solely Nigerian figures of this type are previous: they arrive from the survey spherical of 2014 and 2015, as a result of the 2025 spherical stopped asking.
In that spherical, safety value small corporations 3.9% of their gross sales, medium corporations 4.8% and huge corporations 6.3%. Their losses to theft and vandalism ran the opposite method, falling from 1.8% all the way down to 0.7%.
Larger corporations purchase extra safety and are robbed much less for it. That is the studying, not the discovering: the survey information what corporations spent and what they misplaced, and leaves the explanation to us.
One in 5 giant Nigerian firms now says crime is the worst factor it faces. In international locations at a comparable revenue stage, fewer than 4 in a hundred say so.
Why ought to getting bigger appeal to bother? Because bigger is seen, and on this nation visibility is the factor that prices.
The identical survey requested corporations whether or not they have been registered once they first opened. Among small corporations, 47% have been. Among giant corporations, 78% have been.
Nigerian businesses don’t typically begin formal after which develop. They develop first and floor later, in the event that they floor in any respect.
An unregistered enterprise is tougher to tax, tougher to examine, tougher to levy and tougher to seek out, and each a kind of is price actual cash to the one that owns it.
Nigerians have already got a identify for what comes subsequent. Multiple taxation: the federal income service, the state, the native authorities, then the levies for signage and refuse and surroundings, then the collectors on the gate whose authority no person can set up. Each one is survivable by itself. Together they’re what it prices to be discovered.
Here is the half that issues most. Everything a agency pays for becoming seen arrives without delay, and the whole lot it was promised in return arrives later, if in any respect. The evaluation comes this quarter. The credit score, the safety, the courtroom that may implement your contract, these are available another 12 months.
Set towards that sequence, staying small is not a failure of nerve. It is a appropriate studying of the phrases on supply.
This collection has made a model of that argument earlier than, about merchants who is not going to register and landowners who is not going to title. What the agency knowledge provides is tougher. The penalty doesn’t cease on the door. It grows with you.
The authorities has improved these phrases, and deserves the credit score. Since January, below the brand new tax acts, a qualifying small firm pays no firm revenue tax, no capital features tax and no growth levy.
If tax have been the entire of the issue, corporations would now be surfacing in numbers. It is too early to know. But the reform reaches the a part of the invoice that was written down, and the remainder of the invoice was by no means on a kind: the levies, the visits, the safety invoice. None of that has moved.
None of this displaces the issue Nigerian corporations identify most frequently, which is electrical energy. It leads the listing at each measurement, and at 37% it weighs heaviest on the most important corporations of all. That is the generator financial system, exhibiting the identical gradient.
Power is the heavier burden. The distinction is not weight however certainty: a agency can worth a generator and the diesel to run it, and it can’t worth the danger of being observed.
The different aspect of this argument deserves its strongest kind. Economists have argued for years about whether or not a lacking center exists in any respect.
Hsieh and Olken examined India, Indonesia and Mexico and located no hole in the course of the agency measurement distribution. What they discovered as an alternative was a easy slope, working from very many tiny corporations all the way down to only a few giant ones. Work on African knowledge has reached a lot the identical conclusion in regards to the form.
They are proper in regards to the form, and it doesn’t rescue us. The sharper query was by no means whether or not there is a gap in a chart. It is whether or not medium sized corporations carry the share of the work that an financial system wants them to hold, and in Nigeria they plainly don’t.
A World Bank examine of 4 African international locations discovered exactly that, and located one thing extra helpful moreover. The scarcity doesn’t come from corporations being born too small. It comes from corporations not rising.
Nigerian enterprises usually are not failing to begin. They are failing to get bigger.
What that prices is not summary, and it doesn’t fall on enterprise homeowners. About 92% of employed Nigerians work informally, and amongst employed ladies it is 96%. Informal work means no contract, no discover, no pension and no declare on anyone should you fall in poor health.
A job inside a actual firm is probably the most strange type of safety an financial system can supply a family, and Nigeria has few of them to present. That is what the lacking center really means. Not a curiosity about agency measurement. A working life with no flooring below it.
The different aspect of the lacking center is what occurs on the uncommon events a enterprise does attempt to cross it. When a Nigerian firm goes trying for severe cash, any person from exterior lastly examines it carefully, usually for the primary time in its life.
I’ve spent most of my profession being that individual. The drawback almost all the time arrives in the identical form.
The accounts are audited and the auditor has signed them with out reservation. That appears like the top of the matter. It is not.
An audit checks that what the corporate says occurred did occur. An investor is asking one thing completely different: how a lot of this revenue will nonetheless be there after I’ve paid for it, and what money owed am I about to inherit?
Those questions are settled by paperwork, and the paperwork is often lacking. Is the hire going to a landlord, or to a different firm the proprietor occurs to personal? Is everybody engaged on the premises really on the payroll? The pension deducted from salaries each month, was it ever despatched on, and is there a receipt to show it?
Almost none of this is fraud. It is twenty years of small, smart selections taken by an proprietor with good motive to maintain his head down. But an investor can’t take any of it on belief: something that can not be proved turns into an assumption, and the idea by no means favours the vendor. Every unanswered query comes off the supply.
The warning that stored the enterprise alive is what prices it cash the primary time it tries to grow to be one thing bigger.
So the reply is to not lecture small corporations in regards to the virtues of formalising. They have executed the arithmetic, and on the numbers in entrance of them they’re proper. The work is to alter the arithmetic.
No quantity of urging will repair the order by which the prices and the advantages arrive. Only a higher discount will.
A greater discount is particular, and I’ve argued components of it right here earlier than: a collateral registry that genuinely lets a agency pledge its tools and inventory, credit score bureaus a lender will act on, a title low-cost sufficient to be price acquiring. What the dimensions knowledge provides is the half aimed toward progress relatively than at entry.
Set a printed restrict on what number of authorities could cost a enterprise in any respect, in order that getting bigger stops that means being discovered by extra of them. And watch the brand new thresholds rigorously.
A aid that ends abruptly at a stage of turnover is not an incentive to begin. It is a wall throughout the trail out. It ought to taper, not cease.
The tougher half is not the proprietor’s job. Security is the one value a agency can’t purchase its method out of and can’t insure towards at a smart worth. A rustic that wishes medium sized firms has to make it secure to be one.
And a few of it is ours, on the investing aspect. Patient capital, fairness as an alternative of extra debt, ensures that share the danger of rising relatively than pricing it. The corporations that should be crossing into the center want cash that is not terrified of what crossing includes.
The want is seen in our personal numbers. Across Africa within the first half of this 12 months, the cash put into personal firms rose by about two thirds whereas the variety of offers fell by a sixth. More capital, chasing fewer firms that may survive an examination. That is the lacking center seen from the opposite finish of the desk.
Nigeria doesn’t want forty million businesses. It already has them, and they’re the proof that the ambition was by no means lacking. It wants a few hundred thousand of them to seek out that becoming bigger is well worth the danger.
A trillion {dollars} is not going to come from forty million folks buying and selling tougher. It will come when getting bigger stops costing a Nigerian enterprise greater than it returns.
One in a collection exploring whether or not, and the way, Nigeria can grow to be a one trillion greenback financial system.
- Frank Nnamka is a personal fairness and affect investor. He writes right here in a private capability, and the views expressed are his personal and don’t replicate the place of his employer or any organisation he is affiliated with.