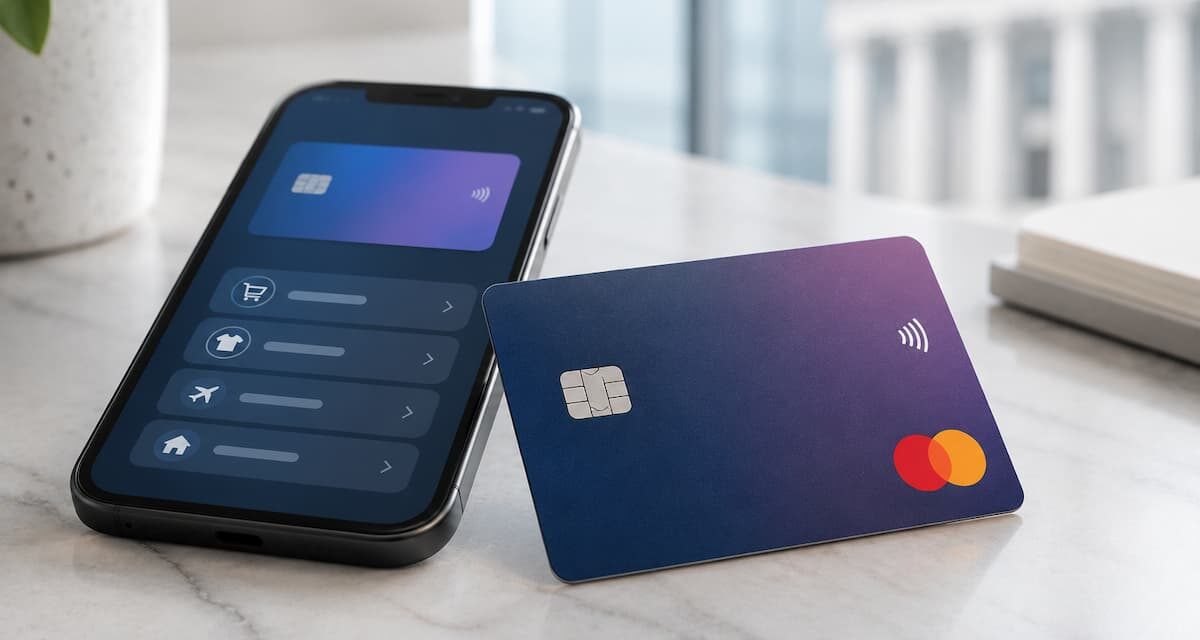

Splitit has introduced the Splitit World Mastercard, a white-label bank card constructed for mid-sized banks and credit score unions that embeds instalment fee performance into on a regular basis card spending. The product is anticipated to attain monetary establishments in early 2027, constructed on Mastercard’s community and branded underneath every issuing establishment’s personal identify.
The card works by a consumer-set spending threshold configured within the financial institution’s personal cellular app. Purchases beneath the edge are settled in full inside 30 days, whereas these above it may be cut up routinely into mounted month-to-month funds. Cardholders retain the flexibility to change a purchase order again to full fee, or to modify the instalment schedule, earlier than their assertion closes. Splitit provides the instalment engine and an AI-enabled cellular expertise that banks embed inside their current digital infrastructure; Mastercard gives the acceptance community, tokenisation, Zero Liability safety and dispute decision.
The strategic case for white-label

Chief government Nandan Sheth framed the product round a structural shift in shopper borrowing preferences: “Banks already have the relationship, the brand and the primary account. What many of them lack is a way to offer instalment plans at the point of purchase without having to build a lending business from scratch. Our white-label card gives them that, under their own name.”
The addressable goal, mid-sized banks and credit score unions, is a phase that has traditionally been unable to compete with bigger issuers or fintech challengers on instalment credit score. Building a proprietary buy-now-pay-later or instalment programme in-house requires vital know-how funding, regulatory approval and underwriting infrastructure. A white-label association shifts that burden to Splitit and Mastercard, whereas permitting the establishment to retain the shopper relationship and the information that comes with it. That knowledge level is more and more consequential as card-linked loyalty and personalisation develop into differentiators in retail banking.
Market context and regulatory backdrop
The instalment credit score market has develop into congested because the first wave of standalone buy-now-pay-later suppliers scaled quickly after 2019. Regulatory headwinds have adopted. In the UK, the Financial Conduct Authority has been transferring in the direction of formal regulation of BNPL merchandise after years of session, and the EU has introduced short-term instalment lending inside the scope of the revised Consumer Credit Directive. These developments have nudged the market away from pure BNPL apps in the direction of card-linked and bank-embedded fashions, which sit inside extra established regulatory frameworks and carry the credibility of an current banking relationship.
Splitit’s mannequin is distinct in that it operates in opposition to current bank card traces reasonably than issuing new credit score. The Splitit World Mastercard extends that positioning right into a full issuing product, which adjustments the regulatory relationship: the issuing financial institution carries the credit score danger and compliance obligations, whereas Splitit gives the know-how layer. That division is probably going to be engaging to establishments that need the product performance with out assuming the function of a brand new credit score originator.
Competitor stress comes from a number of instructions. Established card networks have their very own instalment overlay merchandise, processors are constructing instalment APIs, and a few bigger banks have launched their very own proprietary options. The key differentiator Splitit is claiming is distribution on the mid-market tier, a phase the place the economics of in-house growth not often stack up. Splitit experiences round 4,500 lively retailers throughout 30 international locations on its current platform, which provides it each a service provider acceptance footprint and a knowledge asset that might assist underwriting and product refinement for issuing companions.
AI degree 1 of 5: written by Darlyn Ho; AI helped with tone, construction or wording; edited and signed off by Mark Walker, Editorial Director. What the degrees imply