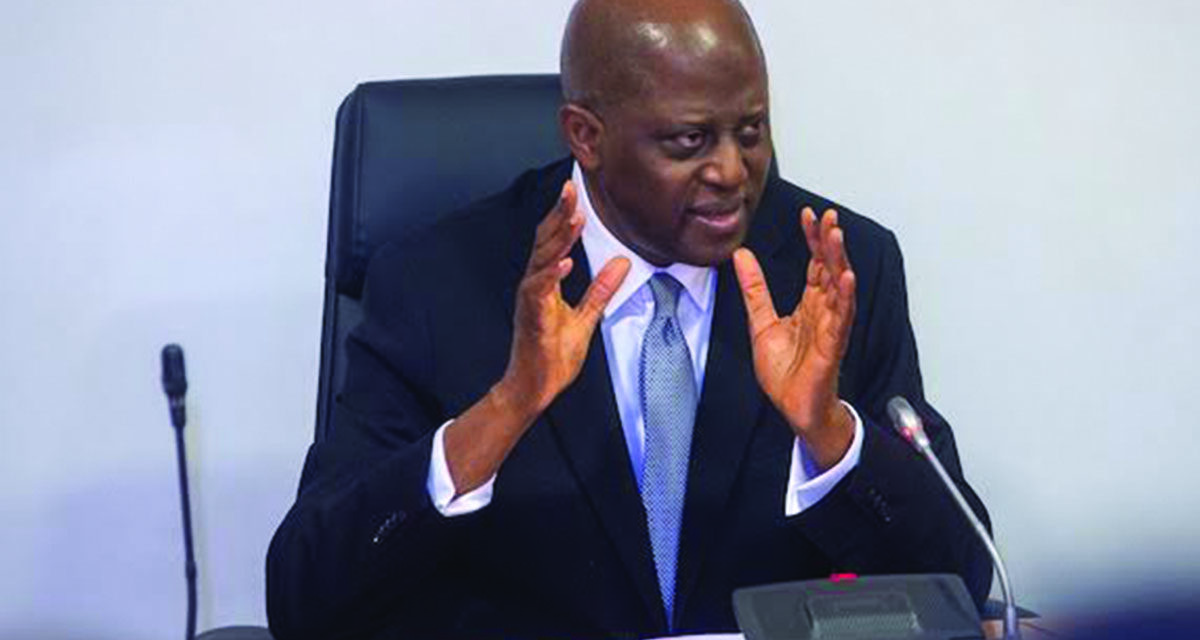

Three years after inheriting a financial system weakened by extra liquidity, FX distortions and collapsing confidence, CBN Governor, Mr. Olayemi Cardoso, is looking for to show hard-won stability into cheaper capital and stronger progress with out reopening the vulnerabilities he spent time to repair, writes James Emejo
There is a refined however essential change within the language coming from the Central Bank of Nigeria (CBN).
For a lot of the previous three years, the dialog was about stopping issues from getting worse—containing inflation, rebuilding reserves, stabilising the naira, draining extra liquidity and restoring confidence in a financial authority that Governor Olayemi Cardoso mentioned he inherited in a deeply weakened state. Now, the query is completely different. With inflation falling, the overseas trade market extra steady, reserves rebuilt and buyers returning to Nigerian markets, the central financial institution is starting to ask whether or not the equipment it used to revive stability should itself be recalibrated.
That is the deeper that means of the Monetary Policy Committee’s determination to reset the Monetary Policy Rate (MPR) by 350 foundation factors to 23 per cent.
The measurement of the discount attracted the headlines. But Cardoso’s rationalization factors to one thing extra consequential: the CBN believes the issue has moved from controlling financial extra to creating financial coverage transmit successfully via an financial system that’s now not the place it was three years in the past.
The MPC has described the transfer as a reset moderately than a standard easing cycle, retaining a excessive Cash Reserve Requirement and stressing that coverage would stay restrictive and data-dependent.
Fighting inflation to fixing transmission
Cardoso insists the newest price determination shouldn’t be mistaken for an abrupt abandonment of the restrictive coverage that outlined the early years of his administration.
The central financial institution believes tightening has performed a lot of the work for which it was deployed.
Inflation, which Cardoso recalled was round 30 per cent when he took workplace, has fallen to fifteen.39 per cent.
The overseas trade market is significantly extra orderly. Gross exterior reserves have risen above $55 billion, in contrast with web reserves of about $3.3 billion at first of his tenure. The stability of funds has moved into surplus, whereas investor confidence has improved.
But one other downside has emerged: the coverage price itself had turn into more and more indifferent from the charges at which cash was truly buying and selling available in the market.
If the benchmark price sends one sign whereas interbank and different market charges ship one other, financial coverage turns into much less efficient.
That is why Cardoso’s most revealing description of the 350-basis-point discount was not “easing”.
It was a “reset and recalibration.”
The goal, in his rationalization, is to shut the hole between the coverage sign and market actuality, strengthen transmission and make sure that the CBN’s selections truly affect the associated fee and availability of cash throughout the monetary system.
This makes the newest transfer much less about abandoning restraint than about altering the mechanism via which restraint is exercised.
FX market reform
Perhaps probably the most consequential a part of Cardoso’s three-year account is his therapy of the overseas trade market. The previous system, based on him, was not merely inefficient. It created a distortion through which entry to overseas trade might rely upon connections and preferential channels.
Multiple trade charges successfully operated as a subsidy.
Cardoso put the price of that distortion at roughly three per cent of GDP—larger than the estimated 2.2 per cent GDP price of the gas subsidy on the time. Taken collectively, the 2 distortions represented a burden equal to about 5.2 per cent of GDP.
The significance of the FX reform subsequently goes past the day by day motion of the naira.
It eliminated a serious supply of uncertainty from financial administration. Businesses can value extra rationally. Investors have higher visibility. Foreign trade can transfer via a extra clear market. And the CBN has higher capability to construct reserves with out continually defending a man-made exchange-rate construction. That stability has now turn into one of many foundations for the newest financial reset.
Remittance shock
One of the quieter indicators of that change is sitting exterior the standard monetary-policy statistics.
Diaspora remittances.
Cardoso mentioned month-to-month inflows had risen from roughly $200 million to about $600 million and have been approaching $1 billion by July.
He was cautious to not current one month as proof of a everlasting pattern. His bigger level was that coverage adjustments had altered the incentives and infrastructure via which Nigerians overseas ship cash house.
The CBN revamped the BVN framework for Nigerians within the diaspora, imposed higher settlement and reporting necessities on worldwide cash switch operators and stepped up engagement with the diaspora.
The result’s probably extra essential than the headline month-to-month determine. Nigeria is more and more capable of appeal to overseas trade via channels which are much less depending on speculative portfolio flows.
That issues now as a result of decrease home yields might make Nigerian fixed-income property comparatively much less enticing to some worldwide buyers. Remittances present a distinct type of buffer.
Rebuilding banks to encourage lending
The financial reset additionally rests on a banking sector that has itself undergone reconstruction.
The recapitalisation train was initially met with scepticism, notably after the naira adjustment and the federal government’s ambition of constructing a $1 trillion financial system.
But the train finally mobilised substantial home capital.
For Cardoso, that isn’t merely a regulatory achievement.
It is proof that home financial savings and funding capability exist in Nigeria when confidence and institutional buildings are sufficiently sturdy.
The goal is now to have banks able to absorbing shocks whereas offering the capital required for a bigger financial system.
That places the banking business straight on the centre of the following part of the CBN’s technique. A decrease MPR can open the door. But banks should stroll via it.
Real check begins with debtors
This is the place the analysts’ reservations turn into essential.
For Chairman, Alliance for Economic Research and Ethics, Dele Kelvin Oye, a decrease coverage price is a chance moderately than a assure.
His warning is simple: the discount should attain companies and households via precise lending charges.
There is a specific hazard that banks might reprice deposits quicker than loans, permitting their margins to widen with out producing the anticipated aid for productive debtors.
His name for a “Prime Lending Rate Adjustment Tracker” goes to the center of the transmission downside.
Chief Executive Officer of the Centre for the Promotion of Private Enterprise (CPPE), Muda Yusuf, equally sees the choice as probably vital for the actual sector, the place costly credit score has constrained funding, working capital and job creation.
Professor Uche Uwaleke of Capital Market Academics of Nigeria believes the macroeconomic situations now justify the discount, whereas NECA’s Adewale-Smatt Oyerinde cautions that companies is not going to really feel significant aid until banks transmit the change.
That distinction is important.
The CBN can cut back the worth of the financial coverage sign. It can’t compel each financial institution to make productive credit score low cost.
The banking sector’s response will subsequently turn into probably the most essential measures of whether or not Cardoso’s recalibration succeeds.
A special type of fiscal-monetary relationship
Another a part of Cardoso’s second act is institutional moderately than numerical.
The new fiscal-monetary coordination settlement between the CBN and the Ministry of Finance is designed to stop financial and financial coverage from working at cross-purposes.
Cardoso’s level is that coordination ought to now not rely upon personalities occupying specific places of work.
That issues as a result of Nigeria is transferring in direction of an inflation-targeting framework.
Monetary coverage can’t sustainably carry that burden alone.
Government borrowing, liquidity creation, debt issuance and public spending can both reinforce or undermine the central financial institution’s efforts to manage costs.
The new framework is subsequently meant to institutionalise communication and coordination with out compromising the CBN’s independence.
Election as subsequent stress check
Perhaps probably the most revealing aspect of Cardoso’s interplay with journalists was his dialogue of the approaching election cycle.
Rather than treating election-related liquidity as an unpredictable occasion, the CBN has modelled eventualities round forex in circulation, banking-system liquidity, financial aggregates and overseas trade demand.
He mentioned the central financial institution doesn’t intend to attend for liquidity pressures to turn into seen earlier than responding. It plans to make use of its financial instruments proactively.
Cash will stay obtainable, Cardoso mentioned, however abuse of the money system is not going to be tolerated.
The emphasis on digital funds, transaction trails and enforcement of money limits is subsequently a part of a broader effort to stop election-related liquidity from undoing the steadiness painstakingly constructed over the previous three years.
Global vote of confidence
The closing piece of the puzzle is Nigeria’s re-entry into main worldwide funding indices. Cardoso described this as a vote of confidence. The significance extends past status. Some world institutional buyers function below mandates that limit funding in markets absent from recognised indices. Restoring Nigeria’s place in these benchmarks can subsequently broaden the investor base, deepen home capital markets and probably enhance overseas trade liquidity. It additionally strengthens financial transmission.
Deeper markets present extra dependable value indicators, broader sources of funding and higher liquidity via which monetary-policy selections can work. That is why the CBN’s reforms can’t be lowered to the MPR alone. The price is just one element of a a lot bigger try to rebuild the monetary structure. From survival to the tougher process of progress.
Three years in the past, Cardoso’s instant problem was credibility.
The central financial institution needed to persuade Nigerians and buyers that it might management liquidity, restore the integrity of the FX market, rebuild reserves and implement the foundations.
Today, the problem is extra demanding. It has to show that stability can produce one thing tangible- cheaper productive credit score, extra funding, deeper capital markets, larger private-sector capability and extra jobs.
And finally, stronger progress with out a return to the excesses that created the unique disaster.
Bismarck Rewane of Financial Derivatives Company captures the transition by arguing that the speed determination needs to be assessed in opposition to the cumulative impression of financial coverage moderately than seen as a single reduce.
That is probably one of the simplest ways to grasp Cardoso’s newest transfer. The CBN shouldn’t be declaring victory over inflation.
Nor is it opening the floodgates.
It is betting that the buffers collected via three years of inauspicious reforms at the moment are sturdy sufficient to permit financial coverage to turn into extra attentive to an financial system that has modified.
The hazard is that the identical buffers could possibly be examined if decrease yields set off portfolio outflows, renewed FX stress or extreme liquidity.
The alternative is that the reset might lastly shut the hole between macroeconomic stability and the expertise of companies that also face punishing financing, power, logistics and manufacturing prices. That is the actual check of Cardoso’s second act.
The first part was about stopping the financial system from bleeding. The subsequent is about making the repaired system work for the financial system.